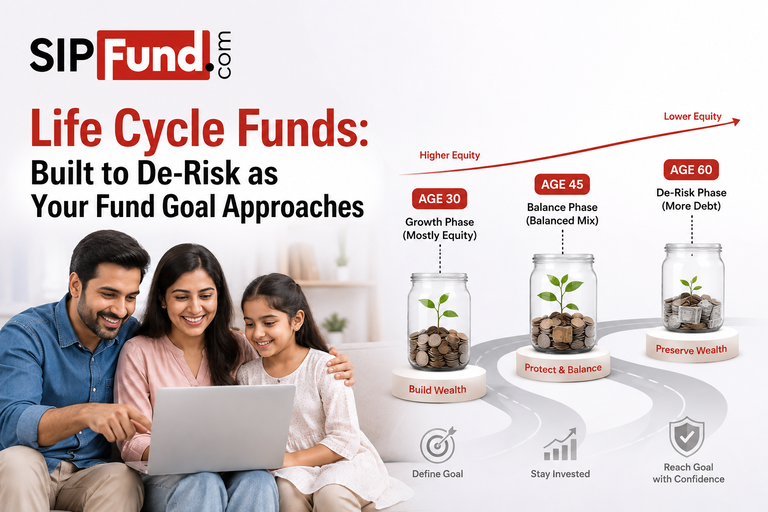
Ritesh is 30, works as a corporate lawyer, and resides in Bangalore with his family. He now has the budget to start investing ₹15,000 monthly in a SIP investment. He attends a financial planning seminar, where the speaker asks,
"If your retirement corpus falls by 30% five years before retirement, do you still have enough time to recover?"
Ritesh realises the answer is no. The reason is that the market crash happened at the wrong time for the retiree example given in the seminar. If the market crash had instead happened, say 20 years before retirement, the retiree would have had time to recover that loss.
The seminar continues, showing that even with a crash happening just 5 years prior to the conclusion of the investment goal, the wealth created could be protected if the fund had been shifted to more debt before the crash.
Ritesh knows that funds are constantly rebalanced by fund managers to maintain their stated investment strategy and asset allocation. But there is probably no fund where the allocation is shifted to less risky investments over the years to protect the money before fund redemption.
Just then, the seminar speaker introduces “Life Cycle Funds. They rebalance with time specifically to protect your money from market crashes”.
Ritesh needed to know more.
What Is a Life Cycle Fund & Glide Path Strategy?
A Life Cycle Fund is a mutual fund that automatically shifts your investments from growth-oriented equity assets to more stable debt assets, as you get closer to your financial goal. The aim: Protect the assets built earlier during the growth phase, from market risks that happen near the goal date.
A Glide Path is a pre-determined plan for gradually changing the fund’s asset allocation over many years. It is a safer strategy of moving investments inside a fund rather than a sudden shift.
The glide path strategy is an integral component of the Life Cycle Funds and is implemented by a Fund Manager; though independently, it can be implemented by an investor in their portfolio.
A Life Cycle Fund’s glide path works like the descent of an aeroplane. The pilot does not suddenly slow down right before the runway; that could lead to a crash; he slowly reduces speed throughout the last part of the journey, using a predefined slowdown plan. In the same way, your money in a life cycle fund slowly “descends” from equity to debt, using a predefined schedule, to lower its risk from market exposure when the fund needs to “land”.
Below is an illustrative example of what the gradual shift of a lifecycle fund may look like:
Illustrative Example: Glide Path of Asset Allocation in a Retirement Fund
Life Cycle Funds also have other winning features:
They were introduced as a new mutual fund category by SEBI in their Master Circular for Mutual Funds, 2026 (Chapter 3, Para 3.8.4, Life Cycle Funds), to replace the earlier “solution-based” fund categories, like retirement funds and children's funds, as the more versatile target-date fund framework. Outside India, it has been popular for decades as Target-date Funds.
Also, a Life Cycle Fund can have investments across multiple asset classes, like Equity, Debt, InvITs, ETCDs, Gold & Silver ETFs, according to SEBI’s Master Circular. This feature makes it generally more flexible than a typical equity fund or debt fund, and it allows fund managers to greatly diversify the investor’s fund and better manage risks.
Why Do Indian Families Need Life Cycle Funds?
Investors usually build their portfolios with 4-6 Equity funds (Large-cap, Hybrid, Small Cap, Mid-cap), and 1 Debt fund (illustrative). This single portfolio would later pay for all their life goals: child’s higher education, child’s marriage, retirement, home down payment, etc.
With such a portfolio setup, investors face many technical challenges. Further, in a market crash, the investor experiences losses that are very difficult to correct.
As an illustrative example, we can journey with the 40-year-old Ritesh into two life choices:
- one where he continues with his 85% equity portfolio till 60, and
- the other where he transfers his funds into three Life Cycle Funds for the remaining 20 years before retirement.
Similar events happen later in each journey, specifically a 35% equity market crash 15 years later, and a 40% market recovery during the next two years.
Reason 1: One Portfolio, Multiple Goals — the Allocation Math Gets Complicated
For an investor using a single fund corpus for all their goals, it is quite difficult to calculate and manage asset allocation that correctly uses different risk-reducing glide paths for the separate goals and different goal journey timelines.
For 15 years, Ritesh diligently invested ₹15,000 monthly in SIPs and built an impressive corpus of ₹73.05 lakh. He used an 85% portfolio to build this wealth and enjoyed a decent 12% average yearly return (simplified assumption) from his allocation strategy. Like many investors, here Ritesh continues with a single fund pool and never shifts the 85% equity allocation.
Reason 2: Separate Portfolios per Goal Mean Too Many Funds to Track
Instead, for better goal clarity, if the investor decides to manage separate groups of debt and equity funds for each of their 4-5 financial goals, that can easily cross 10-15 separate funds in the portfolio. This is not at all recommended.
Ritesh had briefly considered this path after the seminar. But being a corporate lawyer and having a growing family, he wanted to avoid tracking and managing 10-15 funds that systematically matched his goals and their separate glide paths.
Reason 3: Sequence-of-Returns Risk Can Derail a Goal at the Last Minute
The sequence-of-returns risk is about how a sequence of bad yearly returns near a goal's end usually leads to lasting negative outcomes for the portfolio, simply because the portfolio gets less time to recover from the loss before it's used.
Ritesh, now 45, never reallocated his portfolio during 15 years of fund growth; He is sitting on a potential financial risk. He also has multiple goals approaching: College education for his two kids in 8-10 years and retirement in 15 years. Still, he had built an impressive corpus of ₹73.05 lakh through two market crashes. So he continued with the initial asset allocation of 85% equity.
Ten years later, the equity markets crashed by 35% (illustrative).
His goal date is in five years, and his portfolio fell from ₹2.76 crore to ₹1.94 crore (illustrative). The overall decline was by ₹82 lakh (29.71%).
A possible option now can be to delay his goal date, for many of his goals, by many years. For other fixed goals like his children’s education, it would have to be compensated by short-term, risky loans.
Reason 4: Panic Selling After a Crash Locks In the Loss
Seeing ₹82 lakh disappear from his portfolio, just a few years before his goal date, Ritesh understandably starts panicking,
<i>"I have already lost so much. If the market falls another 20%, my retirement will also be ruined."</i>
<i>"Maybe I should sell everything before I lose even more."</i>
Like many investors facing a large loss close to an important financial goal, Ritesh became more focused on avoiding further losses than on his long-term investment plan.
He sells his equity funds and moves everything to debt.
Over the next two years, the market recovers 40% (illustrative). Unfortunately, Ritesh doesn't participate in much of that recovery because he already exited. Even though his debt investments continued to generate positive returns, they grew far more slowly than equities during this strong market recovery. In these two years, his debt investments grew at 7% yearly (simplified assumption), and his portfolio value ended up at ₹2.61 crore. This is still ₹15 lakh short of his last buildup of ₹2.76 crore.
What Life Cycle Funds Do Differently?
A Life Cycle Fund overcomes these for the investor, by creating a single fund for a single goal with a target end date, and the entire allocation drift is managed automatically by the fund manager. The investor’s time and energy are saved.
In a different scenario, Ritesh finally decides to start a Life Cycle Fund at 40, after his second market crash. He asks the questions that he had brushed off after the seminar.
Misconception 1: “Won't my returns be lower if I move to something that shifts to debt?”
This is an understandable concern. But the purpose of gliding is not to maximize the final return; it is just to protect the accumulated money from large losses near the goal date.
Ritesh had started to invest at 30, with ₹15,000 per month that earned an average return of 12% equity and 7% debt. By 40, he would accumulate around ₹33.4 lakh. A clear comparison can be drawn between his corpus after the third market crash. It is assumed that the Life Cycle Fund steps down linearly from 85% equity at age 40 to 20% equity by age 55.
Illustrative: Difference in Ritesh’s Portfolio Value for two Fund Types
85% Equity Portfolio</th><th>Scenario 2:
Life Cycle Fund
(85% to 20% equity glide)</th></tr></thead><tbody><tr><td>Corpus at 40</td><td>₹33.4 lakh</td><td>₹33.4 lakh</td></tr><tr><td>Corpus at 55 (before crash)</td><td>₹2.76 crore</td><td>₹1.96 crore</td></tr><tr><td>Corpus at 55 (after 35% market crash)</td><td>₹1.94 crore</td><td>₹1.82 crore</td></tr></tbody></table>
Even though Ritesh had built a larger corpus by 55 through an 85% Equity portfolio, the same portfolio suffered a more severe loss from the third market crash very close to his goal date, resulting in a lower corpus than the life cycle fund.
It is to be noted that a life cycle fund could have just as easily accumulated less than the equity portfolio after the crash. The deciding factor for Ritesh was saving his corpus from large losses rather than the actual return generated.
Misconception 2: “Do I pay tax for every asset switch between equity and debt inside the Fund?”
No. The gradual changes in asset allocation within a Life Cycle Fund do not generally create a taxable event for the investor. According to India's Income Tax Act, 1961, Capital gains tax is typically triggered when an investor redeems, sells, or transfers their mutual fund units, not when the fund manager buys or sells securities within the scheme as part of the glide path.
Conversely, any manual rebalancing made by the investor in their portfolio would incur capital gains taxes for each sale made. This is an added practical benefit of the Life Cycle Fund.
Misconception 3: "Do I still need separate funds for my two children's education and my retirement?"
Yes, Life Cycle funds are built to serve only one goal. So having three different Life Cycle Funds for his three upcoming life goals - college education for his two kids and his retirement - may seem exhausting. But Ritesh does not need to manage any of the Life Cycle funds. The entire fund with its allocation drift strategy will be taken care of by the fund manager.
The Outcome For Ritesh
After being convinced, Ritesh set up three Life Cycle Funds at 40, from the corpus he had accumulated in his 85% equity portfolio. Fifteen years later, Ritesh is now 55, and he did not have to touch any of his funds.
The 35% market crash happened (illustrative). Ritesh did not have anything to panic about. His funds took care of everything.
Illustrative: Ritesh’s Fund Value. What Happened vs What He Avoided
What He Would Have Faced
(85% Equity, no switch)</th><th>Scenario 2:
What Happened
(Life Cycle Fund)</th></tr></thead><tbody><tr><td>At 40</td><td>₹33.4 lakh</td><td>₹33.4 lakh</td></tr><tr><td>At 45</td><td>₹73.05 lakh</td><td>₹68.47 lakh</td></tr><tr><td>At 55 (before crash)</td><td>₹2.76 crore</td><td>₹1.96 crore</td></tr><tr><td>At 55 (35% market crash)</td><td>₹1.94 crore</td><td>₹1.82 crore</td></tr><tr><td>Change from crash</td><td>– ₹82 lakh (–29.71%)</td><td>– ₹14 lakh (–7.14%)</td></tr><tr><td>At 57 (40% market recovery)</td><td>₹2.61 crore</td><td>₹2.15 crore</td></tr><tr><td>Change from recovery</td><td>+ ₹67 lakh (+34.53%)</td><td>+ ₹33 lakh (+18.13%)</td></tr></tbody></table>
With a life cycle fund that had automatically shifted to 20% equity and 80% debt at 55, the crash cost Ritesh only ₹14 lakh (7%) instead of ₹82 lakh (29.7%). Because so little of his corpus was exposed, there was little reason to panic or sell. The fund simply kept doing what it was built to do.
Ritesh still earned less with his life cycle funds by ₹46 lakh. But that's the price of certainty: never having to face a 30% loss five years before retirement, and never being tempted to sell at the bottom.
Why SIPfund?
SIPfund doesn't currently list Life Cycle Funds as a dedicated category, but you don't need one labeled that way to do what Ritesh did.
Access your SIPfund app here (iOS or Android).
Conclusion
Ritesh didn't need a fund labeled "Life Cycle" to protect his corpus; he needed to shift his allocation before the crash arrived, not after. You can build that same discipline into your own SIP, one category choice at a time.
Prefer to talk it through first? Call us at 95133 55661 /62 /63 /64.
<i>Disclaimer: The information provided in this article is for educational purposes only and does not constitute investment advice or a recommendation to buy or sell any mutual fund. Mutual Fund investments are subject to market risks; read all scheme-related documents carefully.</i>
Responses
Join the conversation
Sign in to share your thoughts and interact with the author.
Sign In to Comment